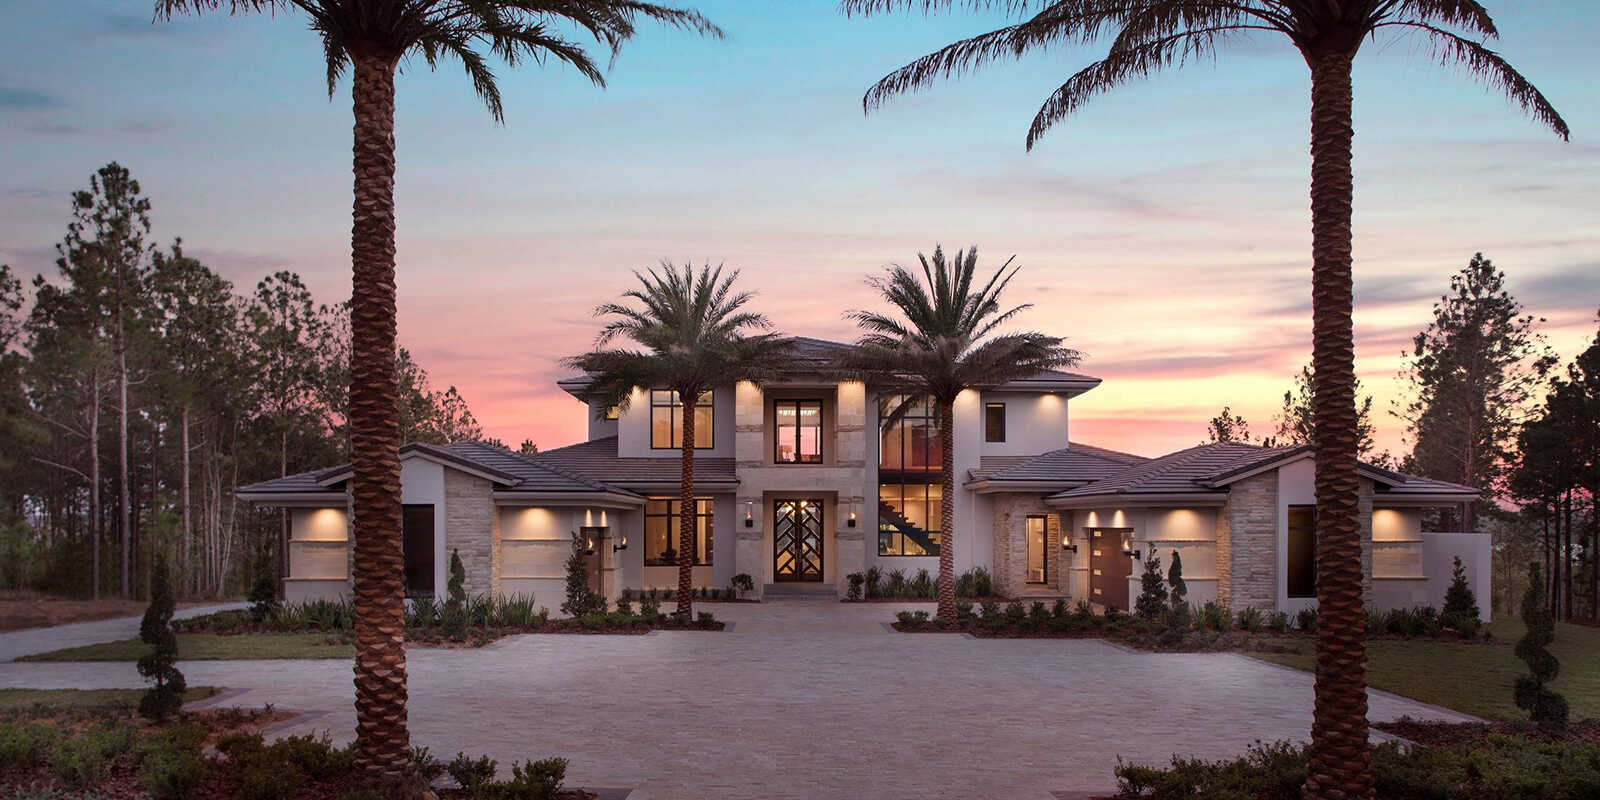
A physician finishing residency may have a signed employment contract, substantial student debt, and a need to relocate to Orlando before the first paycheck arrives. That is precisely the situation physician mortgage programs were designed to address. But are physician loans worth it when the purchase may involve a luxury home in Lake Nona, Windermere, Winter Park, or Dr. Phillips? The answer depends less on the loan label and more on your time horizon, cash reserves, income trajectory, and the property you choose.
A physician loan can be a highly useful financing tool. It can also become an expensive convenience if a buyer overlooks its rate, payment, and resale implications. Sophisticated buyers should evaluate the entire transaction, not simply the down payment requirement.
What Makes a Physician Loan Different?
Physician loans, sometimes called doctor mortgages, are specialized home loan programs for physicians, dentists, veterinarians, and, in some cases, other high-income medical professionals. Eligibility varies by lender. Some programs welcome residents and fellows, while others require an attending position or a particular degree designation.
The defining feature is how lenders underwrite medical debt and future income. A conventional lender may view a large student loan balance as a meaningful liability, even when the borrower has strong earning potential. A physician-loan lender may exclude certain deferred student loan payments from its debt-to-income calculation or use an employment contract to qualify the buyer before employment begins.
These programs commonly offer low down payment options, often with no private mortgage insurance. Depending on the lender and loan amount, qualifying borrowers may purchase with 0%, 5%, or 10% down. For a buyer preserving capital for relocation, furnishings, renovations, or investments, that flexibility can be meaningful.
It is not, however, free financing. The lender is taking on additional risk, and that risk may appear in the interest rate, loan structure, reserve requirement, or pricing at higher loan amounts.
Are Physician Loans Worth It? Start With Your Timeline
The strongest case for a physician loan is usually a buyer who is financially sound but temporarily cash-light. This often includes a physician relocating for a new role, completing training, or moving from renting to ownership in a market where waiting may be costly.
For example, a buyer purchasing a $1 million home with 10% down preserves $100,000 compared with a 20% down payment. If that capital remains in reserve for a move, an emergency fund, or planned home improvements, the physician loan can provide real strategic value. Avoiding private mortgage insurance may further improve the monthly payment relative to certain low-down-payment conventional alternatives.
The calculation changes if you expect to sell within a short period. Buying and selling a home involves transaction costs, and a higher interest rate can matter more when the loan balance stays high. A physician loan may help you buy sooner, but it does not eliminate the need to consider whether you are likely to remain in the home long enough for ownership to make financial sense.
In Orlando, this question is particularly relevant for physicians affiliated with major health systems, medical schools, and specialty practices. A first home near Lake Nona Medical City may be an excellent fit for a long-term position. It may be less suitable if a fellowship, practice partnership, or hospital assignment could take you to another market in two years.
The Difference Between Affording the Loan and Affording the Home
A lender approval is not a lifestyle budget. High-income professionals can qualify for substantial loan amounts, particularly when expected income is used for underwriting. That does not mean the maximum approval is the right purchase price.
Luxury homes can carry significant costs beyond principal and interest. Property taxes, homeowners insurance, HOA fees, pool maintenance, landscaping, utilities, and future capital improvements should be considered before making an offer. In some Orlando communities, insurance costs deserve especially close attention, as premiums and coverage terms can vary materially by property age, roof condition, location, and insurer.
A prudent buyer should model the payment at the actual loan rate, include taxes and insurance, then ask whether the payment still supports retirement savings, student loan strategy, travel, family plans, and liquid reserves. The goal is not merely to close on an exceptional property. It is to own it comfortably.
The Benefits That Can Make a Physician Loan Attractive
The primary benefit is liquidity. A low down payment allows a qualified physician to purchase without draining cash shortly after training or a relocation. This can be especially valuable when a buyer is furnishing a larger home, establishing a household, or maintaining reserves while their new compensation structure becomes established.
The second benefit is student debt treatment. Medical school debt is often substantial, yet it does not always reflect a physician’s actual ability to repay a mortgage. Programs that account for deferred debt or documented future earnings can offer a more realistic path to homeownership than a standard underwriting model.
The third is the potential absence of private mortgage insurance. Conventional loans with less than 20% down often require PMI, which adds a monthly cost until sufficient equity is reached. A physician loan without PMI may be more competitive than it appears at first glance, even if its interest rate is modestly higher.
Finally, some physician-loan programs permit a signed employment contract in place of established pay stubs. For a relocating physician, that feature can shorten the gap between accepting a position and purchasing a home.
The Trade-Offs Buyers Should Price Carefully
Interest rate is the first item to compare. Physician loans can carry higher rates than well-priced conventional financing, especially at 100% financing or in higher loan-balance tiers. A difference that appears small can add up over several years.
Ask each lender for a complete loan estimate, not just a verbal rate quote. Compare the rate, annual percentage rate, lender fees, points, monthly payment, prepayment terms, and whether the rate is fixed or adjustable. If comparing an adjustable-rate mortgage, understand the initial fixed period, adjustment caps, index, margin, and the highest possible payment under the contract.
The second trade-off is equity. With little or no down payment, you begin with limited ownership equity. If market values soften or you need to sell unexpectedly, there may be less room to absorb selling costs. This does not make a low-down-payment purchase wrong, but it makes the holding period and emergency reserves more important.
The third is lender concentration. Not every physician-loan program has the same rules, and eligibility can change by profession, state, credit profile, and loan amount. One lender may allow 5% down on a jumbo purchase while another may require 10% or more. Some will consider an employment contract; others will not. Comparing options is essential.
When Conventional Financing May Be the Better Move
A conventional loan may be preferable when you have a strong down payment, excellent credit, and sufficient income history to qualify easily. With 20% down, conventional financing may offer a lower rate and no PMI, producing a better long-term cost structure.
It may also be wiser if you are purchasing below your maximum budget and have the ability to keep meaningful cash reserves after closing. In that case, the flexibility of a physician loan may not justify a higher rate or fewer pricing options.
Some buyers use a physician loan as a bridge rather than a permanent decision. They purchase shortly after starting a new position, preserve liquidity during the transition, then refinance into conventional financing when their income is documented and their financial picture has matured. That strategy can work, but refinancing is never guaranteed. Future rates, home value, credit, and underwriting standards will determine whether it is advantageous later.
A Better Decision Process for Orlando Buyers
Before selecting a program, define the role the home will play in your life. Is it a five-to-seven-year primary residence near work and family, a long-term luxury property, or an interim purchase while you learn the Orlando market? That answer should shape your financing more than any marketing claim.
Then compare at least a physician-loan option and a conventional option using the same purchase price and estimated closing date. Review how much cash each requires at closing, the full monthly payment, total interest over your expected ownership period, and the reserve balance you will retain after closing. Include realistic property taxes, insurance, HOA assessments, and maintenance allowances.
For luxury and jumbo properties, also examine the property’s marketability. A distinctive estate, large lot, or highly customized residence may be the right lifestyle choice, but it can have a narrower resale audience than a well-positioned home in an established neighborhood. Financing and property selection should support each other.
Working with an experienced Orlando real estate advisor and a lender familiar with physician underwriting can make this process more efficient. The right team helps you evaluate a home, its carrying costs, contract terms, and financing choices as one coordinated decision rather than separate tasks.
A physician loan is worth considering when it protects liquidity, fits a durable ownership plan, and compares favorably with your alternatives after every cost is included. The best choice is the one that gives you confidence at closing and flexibility well after the keys are in hand.