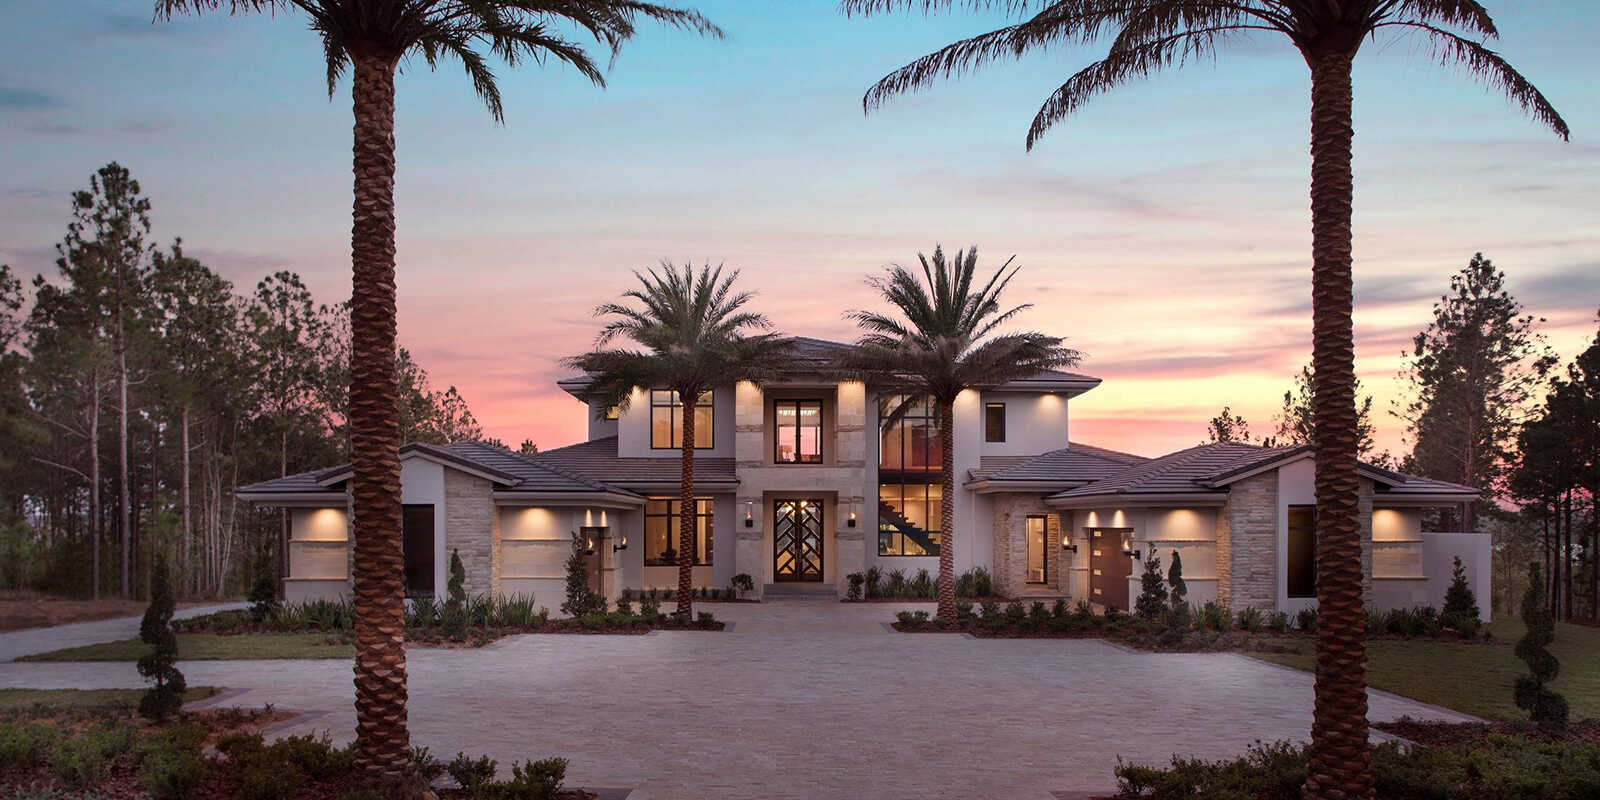
A luxury condo purchase can look straightforward from the listing photos: a Downtown Orlando residence with skyline views, a Winter Park address near Park Avenue, or a Lake Nona unit with full-service amenities. The financing is often where the real work begins. Understanding how to finance luxury condo purchases means evaluating both your personal borrowing profile and the financial health of the building itself before you write an offer.
For a single-family luxury home, the lender is primarily underwriting the borrower and the property. For a luxury condo, there is a third variable: the condominium association. A strong income, substantial down payment, and excellent credit are valuable, but they may not overcome an association with inadequate reserves, unresolved insurance issues, rental restrictions, or pending special assessments.
How to Finance a Luxury Condo Before You Shop
The best time to discuss financing is before touring residences. In competitive Orlando condo markets, a general prequalification may not carry much weight with a seller. A full preapproval, supported by reviewed income, assets, credit, and debt obligations, gives you a credible purchase range and allows your offer to move with confidence.
Luxury buyers should also ask the lender to evaluate the type of documentation that best reflects their financial position. A salaried executive with W-2 income may qualify through a conventional or jumbo mortgage using standard documentation. A business owner, investor, physician with deferred compensation, or buyer whose wealth is concentrated in investments may need a more specialized underwriting approach.
Your preapproval should account for more than the purchase price. The monthly housing payment includes principal and interest, property taxes, homeowners insurance, and HOA dues. In a luxury tower, monthly association fees can be significant because they support staffing, security, elevators, fitness facilities, pools, common-area maintenance, master insurance, and reserves. Those fees are part of the debt-to-income calculation and should be considered from the start.
Calculate the Cash Requirement, Not Just the Down Payment
A buyer focused solely on the down payment can be surprised late in the process. In addition to the down payment and closing costs, lenders may require cash reserves after closing. Reserve requirements are especially common with jumbo financing and may be measured in several months of total housing payments.
A well-prepared buyer also keeps separate liquidity for furnishing, renovations, moving expenses, association initiation fees, and any immediate repairs or upgrades. This is not simply a matter of qualifying. It preserves flexibility after closing and prevents a lifestyle purchase from putting unnecessary pressure on your balance sheet.
Choose the Loan Structure That Fits the Property and Your Profile
The right financing structure depends on the price point, how long you expect to own the condo, your liquidity preferences, and the building’s eligibility. There is no universal best loan for a luxury condo.
Conventional and Jumbo Financing
Conventional financing can be an efficient choice for buyers purchasing within applicable conforming loan limits. Once the loan amount exceeds those limits, most luxury condo buyers move into jumbo financing. Jumbo lenders generally apply more detailed underwriting standards, with close attention to credit history, debt-to-income ratio, assets, reserves, and appraisal support.
Jumbo loans are not automatically more difficult, but the lender and program matter. Some institutions are particularly comfortable with high-net-worth borrowers, variable income, complex compensation, trust assets, or significant investment portfolios. Others follow narrower guidelines. Comparing structure, not just interest rate, is essential.
A fixed-rate mortgage provides payment consistency, which can be attractive for a long-term primary residence. An adjustable-rate mortgage may offer a lower initial rate and make sense for a buyer who expects to sell, refinance, or reposition assets within a defined period. The decision should be based on a realistic ownership horizon, not a guess about where rates may go next.
Portfolio, Asset-Based, and Bank Statement Programs
Portfolio lenders keep certain loans in-house rather than selling them into the secondary mortgage market. That can create flexibility for borrowers whose financial profile is strong but does not fit a conventional underwriting template.
For example, an entrepreneur may have substantial cash flow but limited taxable income after legitimate business deductions. A bank statement program may evaluate deposits rather than relying exclusively on tax returns. An asset-depletion approach may allow qualifying income to be calculated from eligible liquid assets. These options can be useful, but they often come with higher rates, larger down payment expectations, or more restrictive terms.
The right question is not whether a specialized loan is available. It is whether its cost and conditions are justified by the convenience, timing, or liquidity it provides.
Physician, VA, and Foreign National Financing
Physicians and other high-income professionals may have access to financing programs that recognize future earnings potential and the realities of student loan obligations. These programs can be valuable for a doctor relocating to Orlando, though condo approval and association review still apply.
Eligible veterans and active-duty military buyers may consider VA financing, which can offer meaningful advantages. However, the property and project must meet VA requirements, and not every luxury condominium is approved or readily approvable. Early review avoids pursuing a unit that does not fit the program.
Foreign national buyers often use larger down payments and lenders experienced with international documentation, foreign credit, and currency considerations. Requirements vary widely, and funds sourcing must be carefully documented. Buyers purchasing from outside the United States should allow additional time for banking, entity, and documentation questions.
The Condo Association Can Affect Your Loan Approval
This is the issue that distinguishes luxury condo financing from financing a detached home. The lender may need to review the condominium project, association budget, insurance coverage, reserve funding, owner-occupancy levels, litigation history, commercial space, and delinquent dues.
A well-managed building usually makes the process easier. An association with low reserves, deferred maintenance, substantial investor ownership, or active litigation can limit the available financing options. In some cases, a buyer can still proceed through a portfolio lender or with a larger down payment, but the cost and complexity may change.
Insurance deserves particular attention in Florida. Lenders want to confirm that the association carries appropriate master coverage and that the unit owner has any required individual policy, often called an HO-6 policy. Rising insurance costs can also affect association dues, budgets, and future assessments. Review the association’s financial documents with the same care you would apply to the residence itself.
Ask About Assessments and Rental Restrictions
A special assessment is not necessarily a reason to walk away. An assessment for a necessary capital project, supported by a clear plan and responsible association governance, may protect the building’s long-term value. The important question is who pays it, how it is funded, and whether further work is likely.
Rental restrictions also matter. If you want the option to lease the condo in the future, confirm minimum lease terms, rental caps, approval procedures, and short-term rental rules before making an offer. These policies influence both your personal flexibility and the lender’s view of the project.
Protect the Offer With the Right Due Diligence
Your purchase contract should provide enough time for financing, appraisal, association document review, and any building-specific lender requirements. A luxury condo appraisal can be nuanced because comparable sales may be limited, especially in a newer building or a residence with a premium floor plan, private elevator, exceptional view, or extensive upgrades.
An appraisal gap can be managed in several ways: renegotiating the price, increasing your down payment, changing loan structure, or deciding that the home is worth the difference to you. What should not happen is discovering the issue after contingencies have expired because financing conversations started too late.
Coordinate your lender, real estate advisor, insurance professional, and attorney or tax advisor when appropriate. This is particularly valuable for purchases involving trusts, LLCs, 1031 exchanges, investment strategies, or a sale that must close before the new purchase can proceed.
Use Financing as Part of Your Negotiation Strategy
Strong financing can improve more than your approval odds. It can improve your negotiating position. Sellers of high-value condos often prefer buyers who can demonstrate verified funds, a meaningful down payment, realistic timelines, and a lender familiar with condominium underwriting.
Cash is not always the best answer. Even buyers with the ability to pay cash may choose financing to preserve liquidity, retain investment capacity, or manage estate and tax planning goals. Others prefer an all-cash offer for speed and certainty, then consider financing after closing. The better choice depends on the property’s competitiveness, the cost of capital, and your broader financial plan.
For Orlando buyers, the most successful approach is to treat the condo, the association, and the loan as one decision. A desirable address is only part of the investment. With early lender coordination and thoughtful building due diligence, you can pursue the residence you want without allowing avoidable financing details to disrupt the closing.
Luxury Living Orlando helps buyers bring that level of preparation to the search, so the conversation begins not just with where you want to live, but with the ownership strategy that supports it.